Home
» News
»
Current Mortgage Rates: What Homebuyers and Refinancers Need to Know Today
Current Mortgage Rates: What Homebuyers and Refinancers Need to Know Today
Updated September 23, 2026: The latest national benchmark from Freddie Mac puts the average 30-year fixed mortgage rate at 6.95% and the average 15-year fixed rate at 6.26%, based on the week ending September 17. Those averages rose from 6.76% and 6.09%, respectively, one week earlier. For buyers and homeowners considering a refinance, the practical takeaway is simple: mortgage rates are still high enough that small differences between lenders, loan structures, points, and fees can materially change the cost of a loan.
Freddie Mac publishes its Primary Mortgage Market Survey weekly, so the September 17 figures are the latest official weekly averages available as of September 23. They are useful benchmarks, not guaranteed offers. Your actual quote can be higher or lower depending on your credit profile, down payment or equity, loan type, term, property details, points, and lender pricing. See the Freddie Mac Primary Mortgage Market Survey for the latest published averages.
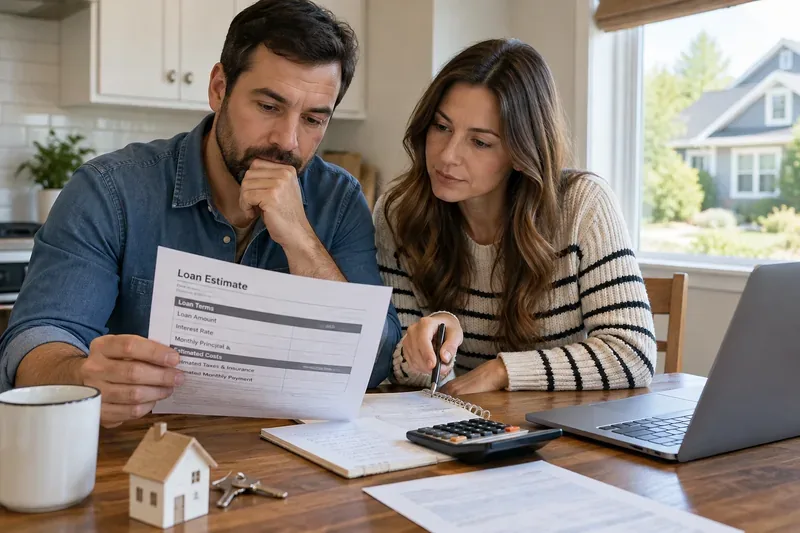
Comparing the interest rate, APR, points, closing costs, and monthly payment on a Loan Estimate gives borrowers a more useful picture than focusing on the headline mortgage rate alone.
Current mortgage rates at a glance
Loan type
Average rate
One week earlier
One year earlier
30-year fixed
6.95%
6.76%
6.26%
15-year fixed
6.26%
6.09%
5.41%
These are national averages from Freddie Mac for September 17, 2026. The 30-year rate increased by 0.19 percentage point in one week, while the 15-year rate increased by 0.17 percentage point. Freddie Mac also reported that the 30-year average was 0.69 percentage point above the same week a year earlier. The historical figures can be checked in the Freddie Mac mortgage-rate archive.
What that rate means in dollars
A rate quote is easier to judge when you translate it into a monthly principal-and-interest payment. On a $400,000, 30-year fixed mortgage at 6.95%, the monthly principal-and-interest payment is about $2,648. At 6.76%, the same loan would be about $2,597. That is a difference of roughly $51 per month, before property taxes, homeowners insurance, mortgage insurance, homeowners association dues, or other housing costs.
The example also shows why waiting for a dramatically lower rate is not the only decision that matters. A buyer who finds the right home and can comfortably afford the payment may still prefer to buy now, especially if the alternative is continuing to rent or risking a higher home price later. Another buyer whose budget is already stretched may reasonably decide that a $50, $100, or $200 monthly difference matters enough to keep shopping, increase a down payment, reduce the target price, or wait. The rate by itself does not answer the affordability question.
Why your mortgage quote may not match the national average
Freddie Mac's average is a market benchmark. A lender prices a specific borrower using more information. The Consumer Financial Protection Bureau says credit score, down payment, loan term, and loan type can all affect the interest rate and total cost. Its mortgage rate exploration tool is designed to show how those variables change borrowing costs, although its displayed lender-rate dataset is not a substitute for a current quote.
Credit is especially important. The CFPB notes that higher credit scores generally make borrowers eligible for lower interest rates and more lender choices. Income, existing debt, savings, assets, and the information in a credit report also matter. Borrowers preparing to apply can review the CFPB's explanation of how credit scores affect mortgage pricing.
Down payment can matter as well. A larger down payment may improve pricing and can reduce or eliminate some forms of mortgage insurance, depending on the loan. But using every available dollar for the down payment can leave a buyer short of cash for closing costs, moving, repairs, or an emergency fund. The better comparison is not simply “largest possible down payment,” but the combination of cash needed at closing, monthly payment, loan costs, and remaining reserves.
Interest rate and APR are not the same thing
One of the easiest mistakes is comparing lenders only by the advertised interest rate. The interest rate is the yearly cost of borrowing the principal. The annual percentage rate, or APR, is broader: it generally incorporates the interest rate plus certain points, broker fees, and other loan charges. The CFPB explains the distinction in its interest rate versus APR guidance.
APR is useful, but it should not be the only comparison. For example, a loan with a lower rate may require substantial discount points paid upfront. If you sell the home or refinance before those points have had time to pay for themselves, the lower rate may not produce the expected savings. Conversely, a borrower who expects to keep the loan for many years may find that paying points is worthwhile.
Example: when points may or may not make sense
Suppose one lender offers a zero-point loan at one rate and a lower-rate option that requires $4,000 in points. If the lower rate saves $80 per month, the simple break-even period is 50 months: $4,000 divided by $80. A borrower expecting to keep that mortgage well beyond 50 months may find the tradeoff attractive. Someone who expects to move or refinance within three years may not.
The CFPB recommends comparing options with and without points or lender credits and considering different time horizons. Its guidance on points and lender credits also notes that one point equals 1% of the loan amount, but the rate reduction obtained for a point varies by lender, loan type, and market conditions.
Should homebuyers wait for mortgage rates to fall?
No single rule works for every buyer. A more useful test is whether the home and payment work under today's numbers without depending on a future refinance. If the payment is comfortable, cash reserves remain healthy after closing, and the property fits your expected time horizon, today's rate may be workable even if rates later decline. A refinance could become an option later, but it should be treated as a possibility rather than a promise.
Waiting can make sense when today's payment would be uncomfortably high, when a borrower can materially improve credit or savings in the near term, or when the purchase would leave too little cash for emergencies. It can also make sense when there is no urgency to buy and the available homes do not justify the monthly cost. What is less reliable is waiting solely because someone predicts a specific mortgage rate by a specific date.
What the Federal Reserve's latest move does—and does not—tell you
On September 16, 2026, the Federal Open Market Committee raised the federal funds target range by 0.25 percentage point to 3.75% to 4.00%. The official decision is available in the September 16 Federal Reserve statement.
That does not mean a 30-year mortgage automatically rises by 0.25 percentage point. Fixed mortgage rates are influenced by longer-term market rates and mortgage-backed securities pricing, as well as lender-specific costs and borrower risk. The Federal Reserve's July 2026 Monetary Policy Report describes agency mortgage-backed securities yields as an important factor in the setting of home mortgage interest rates. In other words, the Fed matters, but the mortgage market can move before a Fed meeting, after it, or even in a different direction from a one-day policy-rate change.
When refinancing is worth a closer look
Refinancing means replacing an existing mortgage with a new one. A lower rate can reduce the monthly payment or total interest cost, but refinancing also usually brings closing costs and fees. The CFPB mortgage glossary notes that borrowers should separate savings caused by a lower interest rate from savings caused by stretching the balance over a longer new term.
Consider a simplified example. A new $350,000, 30-year fixed loan at 6.95% has principal and interest of about $2,317 per month. A new 30-year loan of the same size at 7.75% would be about $2,507 per month, a difference of roughly $191. If a refinance costs $6,000, a crude break-even calculation based only on that payment difference is about 31 months. But a real decision also needs to account for the remaining term on the old loan, new loan term, taxes, insurance, mortgage insurance, points, prepaid items, and whether closing costs are paid in cash or rolled into the new balance.
A refinance is more compelling when the new loan produces meaningful savings, the borrower expects to keep it beyond the break-even period, and the new term does not quietly increase long-run interest expense. It is less compelling when the rate difference is small, closing costs are high, the homeowner expects to sell soon, or the new loan restarts a long amortization schedule that offsets much of the apparent monthly savings.
How to compare mortgage offers today
The most useful comparison is between actual Loan Estimates for the same type of loan, requested close enough together that market conditions are comparable. The CFPB's Loan Estimate explainer shows where to find the interest rate, projected payments, closing costs, points, lender credits, cash to close, and other terms.
Match the loan structure. Compare the same term, rate type, loan type, and approximate lock period.
Check points and credits. A lower rate is not automatically cheaper if it requires more upfront cash.
Compare APR and total loan costs. These help expose differences that the headline rate may hide.
Look at cash to close. A loan that saves $40 per month may not fit if it requires thousands more upfront.
Use your expected holding period. The best choice for a homeowner staying three years can differ from the best choice for someone staying 15 years.
Bottom line for September 23, 2026
Mortgage rates are hovering close to 7% on the national 30-year fixed benchmark, and the latest Freddie Mac reading moved higher week over week. That makes shopping and loan structure especially important. Homebuyers should judge affordability using the payment they can obtain now, not a hoped-for future rate. Refinancers should focus on net savings after costs and on how long they expect to keep the new loan.
The next useful step is to collect comparable Loan Estimates from multiple lenders and evaluate rate, APR, points, fees, cash to close, and monthly payment together. National averages tell you where the market has been; a properly compared set of same-day or near-same-day offers tells you what the market means for you.